


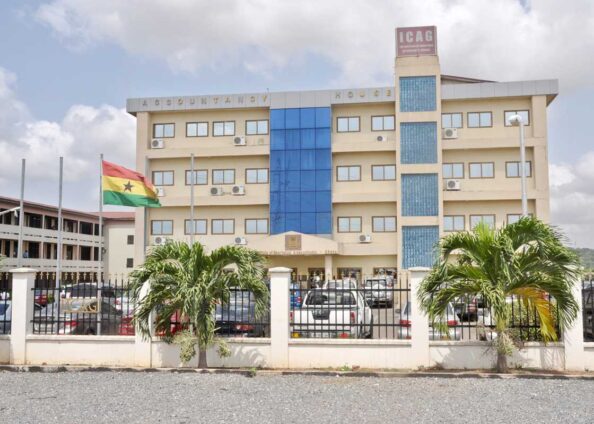
The Institute of Chartered Accountants, Ghana (ICAG) has secured a major legal victory after the High Court affirmed its exclusive statutory mandate to regulate, train, certify and admit professionals into the accountancy profession in Ghana.

The ruling, delivered in a case involving the Chartered Institute of Certified Tax Accountants, Ghana, the National Accreditation Board, ICAG and the Attorney-General, establishes that all branches of accountancy, including tax accounting, fall under the regulatory jurisdiction of ICAG.
In a statement issued on Tuesday, June 23, ICAG said the judgment reinforces the legal framework governing the accountancy profession and serves as a clear warning to organisations seeking to offer professional accounting qualifications without lawful authority.
According to the institute, the High Court ruled that the training, certification, admission and regulation of persons practising any discipline of accountancy are matters exclusively reserved for ICAG under Ghanaian law.
The court also declared unlawful the activities of the Chartered Institute of Certified Tax Accountants, Ghana, which sought to regulate and certify individuals as Chartered Certified Tax Accountants. Consequently, the organisation has been restrained from advertising, training, certifying and admitting persons into such membership programmes.
The judgment is expected to have significant implications for professional accounting education and certification in Ghana, particularly in specialised fields such as taxation and financial reporting.
ICAG explained that its regulatory authority is derived from the Institute of Chartered Accountants, Ghana Act, 2020 (Act 1058), which grants the institute sole responsibility for regulating the accountancy profession in the country.
“The legal position has been further strengthened by the Institute of Chartered Accountants, Ghana Act, 2020 (Act 1058), which vests in the Institute the sole statutory mandate to regulate, train, examine, certify and admit persons into the accountancy profession in Ghana,” the statement said.
Following the ruling, ICAG urged students, employers, educational institutions and the general public to exercise caution when enrolling in professional accounting programmes or relying on qualifications offered by organisations claiming authority to regulate or certify accountants.
The institute warned that any institution, body or organisation presenting itself as authorised to train, certify, license or regulate accounting professionals in Ghana without the requisite legal backing could be acting unlawfully.
It further cautioned that qualifications issued by such entities may not enjoy legal recognition under Ghana’s regulatory framework.
“Any such representation is liable to be challenged under the applicable laws of Ghana,” ICAG stated.
The institute reaffirmed its commitment to protecting the integrity and credibility of the accountancy profession, indicating that it would continue taking appropriate measures to prevent unauthorised institutions from misrepresenting themselves as professional accounting bodies.
ICAG also emphasised the need to maintain uniform professional standards in accounting practice in order to safeguard public confidence in financial reporting, taxation and auditing.
Established under the Chartered Accountants Act, 1963 (Act 170) and later reconstituted under the Institute of Chartered Accountants, Ghana Act, 2020 (Act 1058), ICAG is Ghana’s principal professional accountancy body. It is responsible for promoting the study and practice of accountancy, regulating members of the profession and ensuring compliance with professional and ethical standards.
Under the Companies Act, 2019 (Act 992), members of ICAG are recognised as the professionals authorised to undertake statutory audits of company accounts in Ghana.
Industry observers believe the ruling provides long-awaited legal clarity on the regulation of accounting and tax-related professional qualifications, while strengthening efforts to protect students, employers and the public from potentially misleading certifications.


