


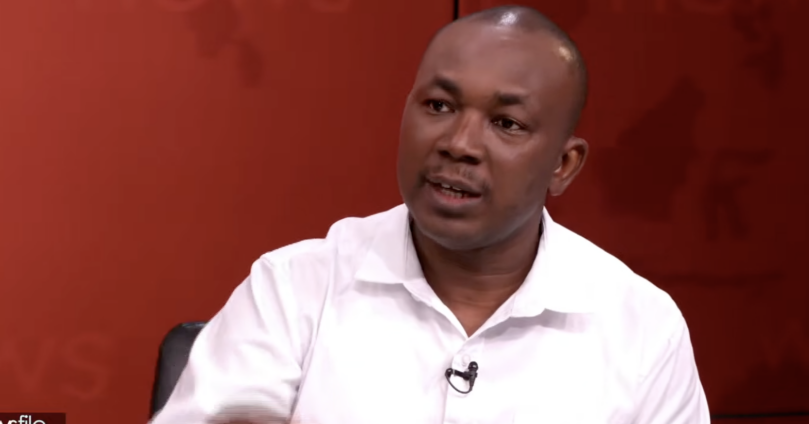
Economist Professor Godfred Alufar Bokpin has cautioned against attributing Ghana’s recent macroeconomic stability to the Ghana Gold Board (GoldBod), arguing that the broader improvement is primarily the result of fiscal and monetary policy.

Prof. Bokpin, however, acknowledged GoldBod’s role in reducing gold smuggling and increasing the amount of foreign exchange generated from gold exports that remains within the formal economy.
“You can see that the gap has narrowed significantly with the introduction of Gold Board. And I think that is a credit to Gold Board,” he said.
GoldBod and foreign exchange inflows
According to Prof. Bokpin, both the New Patriotic Party (NPP) and the National Democratic Congress (NDC) identified challenges surrounding illegal mining, gold production and the accurate reporting of gold exports ahead of the 2024 general elections.
He said the NPP proposed reducing the final withholding tax on gold exports from artisanal and small-scale mining to encourage greater declaration of gold production.
The NDC, on the other hand, opted to establish GoldBod as the principal entity responsible for purchasing and exporting gold, particularly from artisanal and small-scale miners.
Prof. Bokpin said the GoldBod framework has helped channel foreign exchange into Ghana that could previously have been lost through gold smuggling.
He nevertheless stressed that the programme must be assessed against the significant financial costs associated with its implementation.
Programme has incurred significant losses
Prof. Bokpin said the domestic gold purchase programme, for which GoldBod became the main public face from 2025, has resulted in substantial losses.
“This whole domestic gold purchase arrangement for which Gold Board essentially became the face of it from 2025 has also come at a significant loss to us, has come at a significant loss,” he said.
He attributed some of the losses to weaknesses in the design of the programme, arguing that better planning and expert input could have helped avoid them.
“They were design defects of the program,” he said.
He also warned against evaluating GoldBod solely on the basis of its contribution to foreign exchange inflows while overlooking the financial burden associated with the intervention.
Macroeconomic stability driven by fiscal and monetary policy
Prof. Bokpin rejected the suggestion that GoldBod should receive primary credit for Ghana’s improved macroeconomic conditions.
“In fact, that is not the job of the Gold Board. Macroeconomic stability comes from essentially fiscal and monetary policy, which is the Bank of Ghana and all of that,” he said.
He argued that the programme’s benefits must therefore be weighed against its costs, particularly the losses incurred through the domestic gold purchase arrangement.
According to Prof. Bokpin, the losses associated with the programme could be higher than the figures currently being cited.
“Now, we are talking about 22 billion Ghana cedis or 1.7 billion Ghana cedis. In fact, Evans, let me put this across, that if you adopt a holistic approach and look at the whole intervention we put in place, the losses actually exceed the $1.7 billion we are talking about here,” he said.
Tax revenue implications
Prof. Bokpin also pointed to the abolition of the 1.5% withholding tax on artisanal and small-scale gold production, arguing that the policy has additional fiscal implications for the state.
“So, you have all these losses sitting on the books of the Bank of Ghana. Is that okay? In addition to that, we had to abolish the 1.5%,” he said.
He said the fiscal cost becomes more significant when the value of gold exports from artisanal and small-scale miners is considered.
“If you look at the total gold exports from artisanal small-scale miners, which are more than $10 billion, is that okay?”
He argued that the revenue forgone through the tax change could otherwise have supported public spending on infrastructure and essential services.
“We have to give up that one also,” he said.
GoldBod’s gains should not be overlooked
Despite his concerns, Prof. Bokpin acknowledged the positive contribution GoldBod has made to the formalisation of gold-related foreign exchange inflows.
“I recognise the impact of Gold Board, and I celebrate the progress that they have made in terms of crowding in gold-related FX,” he said.
However, he maintained that the programme’s financial losses should form part of any comprehensive assessment of its performance.
“I think that if you look at the benefit in terms of the macroeconomic stability and all of that, I will say that the benefit is quite substantial, but we must also recognise the cost, the huge cost associated with implementing this intervention,” he said.
Exit plan being pursued
Prof. Bokpin said the government, GoldBod and the Bank of Ghana have recognised that the current level of losses cannot be sustained indefinitely.
“The reason I’m saying so is that the government itself, together with the Gold Board and the Bank of Ghana, recognise that these losses are not sustainable going forward,” he said.
He noted that an exit strategy is being pursued as the Bank of Ghana seeks to reduce its direct exposure to the domestic gold purchase programme.
According to Prof. Bokpin, the proposed arrangement is expected to reduce the losses associated with the programme from levels estimated at about 14.5% to 17% to approximately 5% going forward.
He said the transition would be critical to ensuring that the gains from increased foreign exchange retention through GoldBod are achieved without imposing an unsustainable financial burden on the state.


